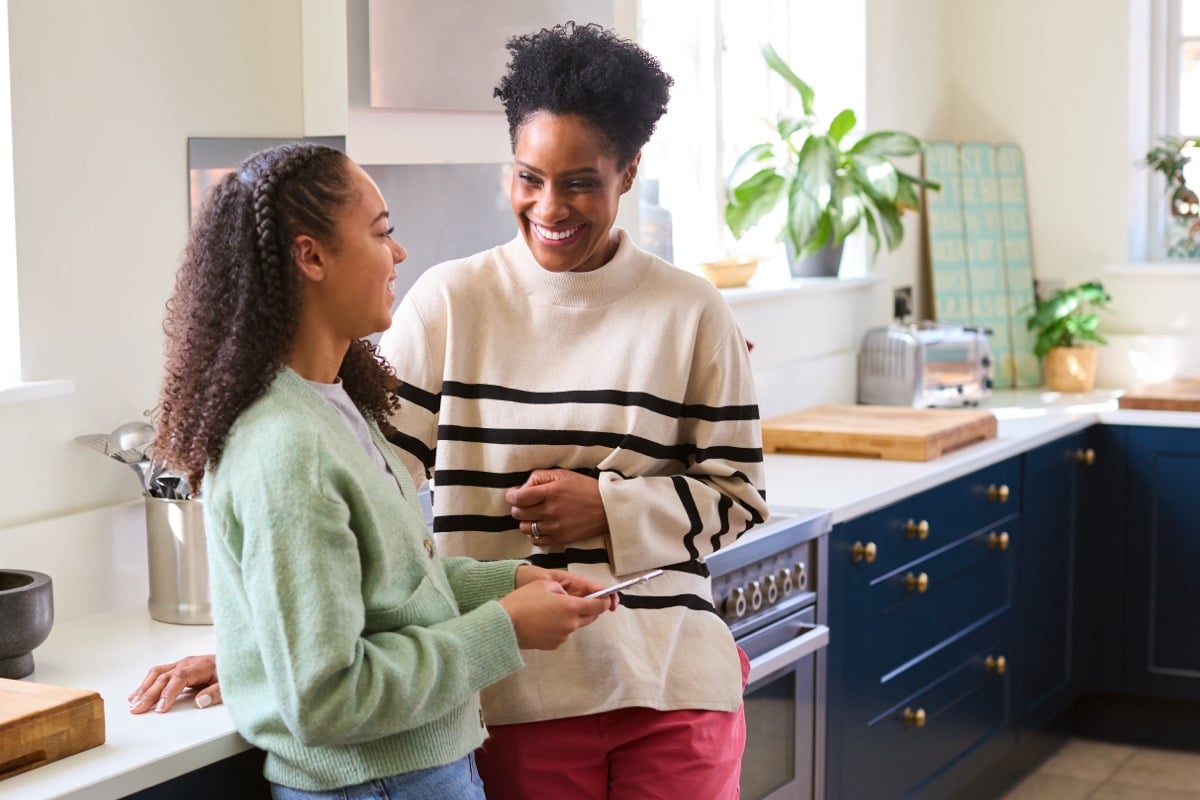
My daughter is Gen Z. Like many teenagers today, she’s ambitious, independent, and learning to balance school and a part-time job.
As a parent, I thought helping her open her first checking account would be easy. I was wrong.
I’ve banked with the same financial institution for years. They know me. They know my accounts, my history, and my financial habits. So, when my daughter started earning a paycheck, I assumed I could quickly open a joint checking account online and help her begin building healthy financial habits.
Instead, I hit a wall. The only option was (gasp!) to visit a branch.
In theory, that doesn’t sound unreasonable. In practice, however, it meant coordinating schedules between a working parent and a teenager balancing school and work, finding branch hours that worked for both of us, and making an errand out of something that felt like it should take minutes online.
We never made it to the branch. Instead, I opened an account for her in just a few minutes online. The process was simple, digital, and designed around how families actually live today.
The result?
My daughter’s direct deposits are now going somewhere other than my primary financial institution: they’re going to a fintech. And that’s where the story gets interesting.
Financial Institutions Are Losing Gen Z Relationships Before They Begin
Banks and credit unions spend enormous amounts of money acquiring new applicants. Yet many are making it surprisingly difficult for existing accountholders to bring family members into the relationship.
My bank didn’t lose a checking account because of rates, fees, or a better offer from a competitor. They lost it because opening an account required too much effort.
The irony is that I was already a customer. I wasn’t asking the bank to onboard a stranger. I was trying to extend an existing relationship to my child.
The customer acquisition opportunity was sitting right in front of them. But instead, a fintech captured it.
This isn’t a criticism of branches. Branches still serve an important purpose, particularly for complex financial needs. But opening a basic checking account for a teenager shouldn’t require the same process as applying for a commercial loan.
What Does Gen Z Really Want From Their Banking Experience?
Gen Z has grown up in a digital-first world. They order food, communicate with friends, complete schoolwork, and manage much of their lives online. Their expectations are shaped by the simplest digital experiences they encounter across industries.
When they experience friction, they don’t wait. They move on. And often, parents move with them.
Family Banking: The Ultimate Strategy for Growth and Retention
Financial institutions talk frequently about lifetime accountholder value. Yet the transition from parent banking relationship to child banking relationship is often fragmented.
Family banking should be one of the easiest growth opportunities available to community banks and credit unions. Imagine logging into online banking and seeing a simple option: “Open an account for your child.”
A few clicks. Identity verification. Required approvals. Digital signatures. Done.
Instead of losing deposits to fintechs and digital challengers, financial institutions could deepen relationships across generations. More importantly, they could help families teach financial literacy at the exact moment young people begin earning and managing money.
Convenience Is No Longer a Feature – Digital Account Opening Is the Baseline
For years, banks and credit unions viewed digital account opening as a competitive advantage. Today, customers and members see it as a basic expectation.
The question is no longer whether digital onboarding is available. It’s whether the process is intuitive enough to complete in the flow of everyday life.
Parents are busy. Teenagers are busy.
If opening an account requires coordinating schedules and driving to a branch, many families will simply choose another option.
That’s exactly what happened in my case.
What Is Account-Opening Friction Actually Costing Financial Institutions?
My bank didn’t just lose one checking account. They lost the opportunity to become my daughter’s primary financial institution.
They lost her paychecks. They lost future opportunities to provide savings products, credit cards, student loans, and eventually a mortgage. All because a process that could have happened online required a branch visit.
As financial institutions think about growth, retention, and the future of banking, there is an important question to consider: How many next-generation accountholders are being lost not because of competition, but because of friction?
For my daughter, the answer is one. For the industry, it’s likely much bigger.
It Starts at Home: Winning the Next Generation With Family Banking
As Gen X parents, many of us are at a unique crossroads. We’ve embraced digital banking ourselves, but we’re also helping our Gen Z children navigate their first financial decisions. We remember balancing checkbooks and visiting branches, while our kids have grown up expecting everything to happen from a smartphone in minutes.
Financial institutions have a tremendous opportunity to bridge these generations by making family banking seamless, intuitive, and digital-first. Those that make it easy for parents to bring their children into the relationship won’t just gain a new account – they’ll earn the trust and loyalty of the next generation of accountholders.
Ready to turn household relationships into a long-term growth engine? Download our white paper to see how rethinking the way you engage families, design account structures, and deploy technology can help you move beyond traditional acquisition tactics to attract and retain the next generation of accountholders.